
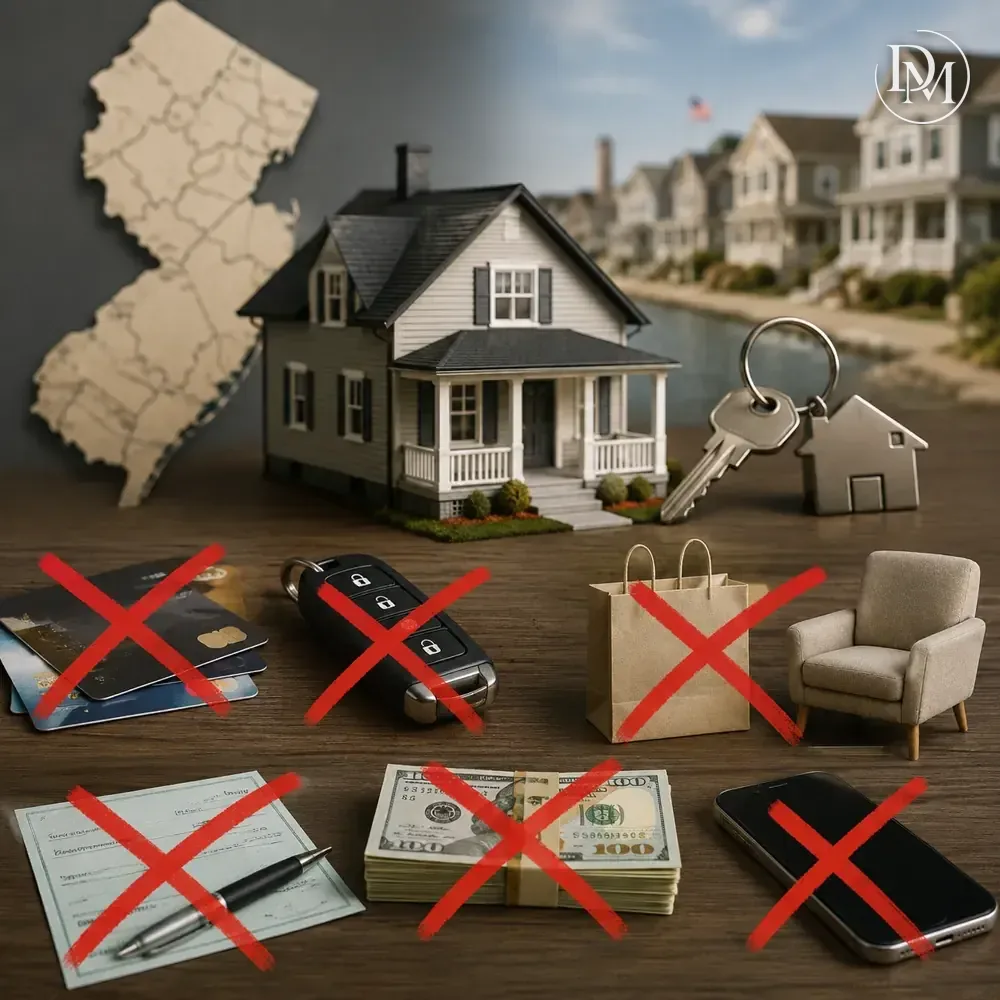
What NOT to Do Before Closing on a Home (New Jersey 2026 Hyper-Local Guide)

Published | Posted by Dennis Mark Interdonato

  • closing
  • Home Buying
  • Insider Insights

Buying a home in New Jersey, whether it’s in Monmouth County, Middlesex, Ocean County, or coastal towns like Sea Girt, Red Bank, or Point Pleasant, is already competitive. The last stretch before closing is where many deals quietly fall apart.

Even strong buyers with solid pre-approvals can lose a home days before closing due to preventable mistakes.

This guide breaks down exactly what NOT to do before closing on a home in New Jersey, so you can protect your mortgage approval, your deposit, and your future home.

Why the Final Days Before Closing Matter So Much in NJ

New Jersey is a high-demand, high-turnover housing market. Lenders often re-verify your finances right before closing, and sellers expect a smooth, predictable transaction.

That means:

  • Any financial change = risk to your approval
  • Any new debt = potential loan denial
  • Any delay = possible contract breach

Even small decisions can trigger underwriting issues.

10 Things NOT to Do Before Closing on a Home

1. Do NOT Change Jobs (or Quit Your Job)

Lenders verify employment right before closing, sometimes even the day before.

Avoid:

  • Changing employers
  • Switching from W-2 to 1099
  • Reducing hours or commission structure changes

Even a “better job” can delay or cancel your loan.

2. Do NOT Open or Close Credit Accounts

This is one of the biggest closing killers in New Jersey transactions.

Avoid:

  • New credit cards
  • Auto loans (especially common before closing!)
  • Financing furniture or appliances
  • Closing old credit cards (it can drop your score)

3. Do NOT Make Large Purchases

Lenders monitor your bank accounts all the way to closing.

Avoid:

  • Buying a car
  • Expensive furniture
  • Jewelry or luxury items
  • “Buy now, pay later” services

Even a $500 purchase can trigger underwriting review.

4. Do NOT Move Money Around Without Documentation

New Jersey lenders require a clear “paper trail” for all funds.

Avoid:

  • Transferring large sums between accounts
  • Depositing cash without explanation
  • Receiving undocumented gifts

If you must move money, document everything.

5. Do NOT Co-Sign a Loan for Anyone

Helping a friend or family member can hurt your approval instantly.

Why?

  • It increases your debt-to-income ratio
  • It appears as new financial liability

6. Do NOT Miss Any Loan Conditions or Deadlines

In NJ contracts, timing is everything.

Avoid:

  • Delayed document submissions
  • Ignoring lender requests
  • Waiting too long on insurance or appraisal issues

Even a 24-hour delay can push closing back.

7. Do NOT Make Big Bank Deposits Without Explanation

Lenders flag “sudden money” immediately.

Avoid:

  • Cash deposits over a few hundred dollars without documentation
  • Unexplained transfers from friends/family
  • Selling items and depositing proceeds without proof

8. Do NOT Cancel Utilities or Insurance Too Early

A common mistake in New Jersey closings.

Wait until:

  • You have official confirmation of recording
  • Your attorney or closing agent confirms funding

9. Do NOT Ignore Home Inspection or Repair Agreements

Especially in competitive NJ markets like:

  • Monmouth County
  • Middlesex County
  • Bergen County suburbs

If repairs were negotiated:

  • Confirm completion in writing
  • Get receipts or inspection sign-off

10. Do NOT Assume “Nothing Can Go Wrong Now”

This mindset causes the most last-minute issues.

Even after final approval:

  • Lenders can re-pull credit
  • Employment can be re-verified
  • Bank statements can be updated

Stay financially stable until the keys are in your hand.

New Jersey Hyper-Local Insight: Why This Matters More Here

In markets like:

  • Sea Girt
  • Manasquan
  • Red Bank
  • Middletown
  • Hoboken
  • Jersey City

Homes often have multiple backup offers, meaning if your financing is delayed or jeopardized, sellers may move on immediately.

In NJ real estate, “almost closed” is not closed.

FAQs: What NOT to Do Before Closing in New Jersey

1. Can I buy furniture before closing on a home?

No. Even financing furniture can impact your debt-to-income ratio and cause loan denial.

2. Will changing jobs really affect my mortgage approval?

Yes. Even a positive job change can trigger re-verification and delay or cancel closing.

3. Can I use my credit card before closing?

Only for normal, small, routine purchases. Avoid large balances or new accounts.

4. Can I deposit cash gifts before closing?

Yes, but only if fully documented with a gift letter and proper sourcing.

5. Why do lenders check everything again right before closing?

Because your financial profile must remain consistent from approval to funding.

6. Can a small purchase really delay closing?

Yes. In New Jersey lending, even small changes can trigger underwriting reviews.

7. Should I stop using my credit cards completely?

No, but keep spending stable and predictable until after closing.

Final Thoughts

The final days before closing are not the time to make financial changes. In New Jersey’s fast-moving housing market, protecting your approval is just as important as finding the right home.

If you stay consistent, avoid new debt, and keep documentation clean, your closing will move smoothly, and you’ll get the keys without surprises.

Keep Reading Insider Insights

Keep reading other bits of knowledge from our team.

Is Buying Before the Holiday Season a Smart Real Estate Strategy? A New Jersey Homebuyer's Guide

The holiday season is approaching, and while many people are preparing for Thanksgiving gatherings, holiday shopping, and year-end celebrations, some New Jersey homebuyers are asking an important question: Should I buy…

By Dennis Mark Interdonato ·

Can You Remove Someone From a Mortgage Without Refinancing? What New Jersey Homeowners Need to Know

Divorce, separation, financial changes, or a change in property ownership can leave New Jersey homeowners asking an important question: Can you remove someone from a mortgage without refinancing the home? The short…

By Dennis Mark Interdonato ·

What Purchases Should You Avoid Before Closing on a Mortgage? A New Jersey Homebuyer's Guide

Your mortgage is almost approved, your closing date is approaching, and you're already planning how to decorate your new home. But could buying furniture, financing a new car, or opening a credit card put your home…

By Dennis Mark Interdonato ·

Buying a Home in Monmouth County, NJ: What Does a 7% Mortgage Really Cost?

Thinking about buying a home in Monmouth County, New Jersey, but wondering what a 7% mortgage rate would mean for your budget? You're not alone. For many prospective homebuyers, the biggest question isn't simply…

By Dennis Mark Interdonato ·

More Homes, Fewer Buyers: How New Jersey Homebuyers Can Negotiate a Better Deal in Today's Market

More homes on the market and fewer competing buyers could create new opportunities for New Jersey homebuyers. But knowing when to negotiate, what to ask for, and how to recognize a good deal can make all the…

By Dennis Mark Interdonato ·

Bulkhead Checks Before You Buy a Waterfront Home: What to Ask For and Who Looks at It

A standard New Jersey home inspection leaves out sea walls, bulkheads and docks, so the bulkhead needs its own look from a marine contractor or a New Jersey licensed professional engineer. Pair that look with the…

By Dennis Mark Interdonato ·

Can You Add a Dock or Boat Lift After You Buy? What to Check Before Closing

Often you can, but not without approval first. In New Jersey, building or changing a dock, pier, piling or boat lift at or below the mean high water line needs an NJDEP coastal permit, a structure on State-owned…

By Dennis Mark Interdonato ·

How Deep Is the Water Off the Dock? Checking Depth, Tides and Bridge Clearance Before You Buy

Check three things before you fall for a dock: the depth on a NOAA nautical chart, the tide predictions from NOAA Tides & Currents, and the clearance of every bridge between the house and open water. Then measure the…

By Dennis Mark Interdonato ·

Flood Vents and Flood Openings on a Raised Home: What Counts and Why It Matters

Flood vents, which FEMA calls flood openings, are permanent openings low in the walls of a crawlspace or the enclosed area under a raised home that let floodwater flow in and out on its own, so the water pressure on…

By Dennis Mark Interdonato ·

View All Articles

Have Questions About This Article? Contact Us Below

Have a question about this article or want to learn more?

Have a question? Get your answers right now.Dennis Mark’s AI Concierge answers your questions without you having to commit to anything up front.

Schedule a Call with Dennis Mark

Or send Dennis Mark a message:








