
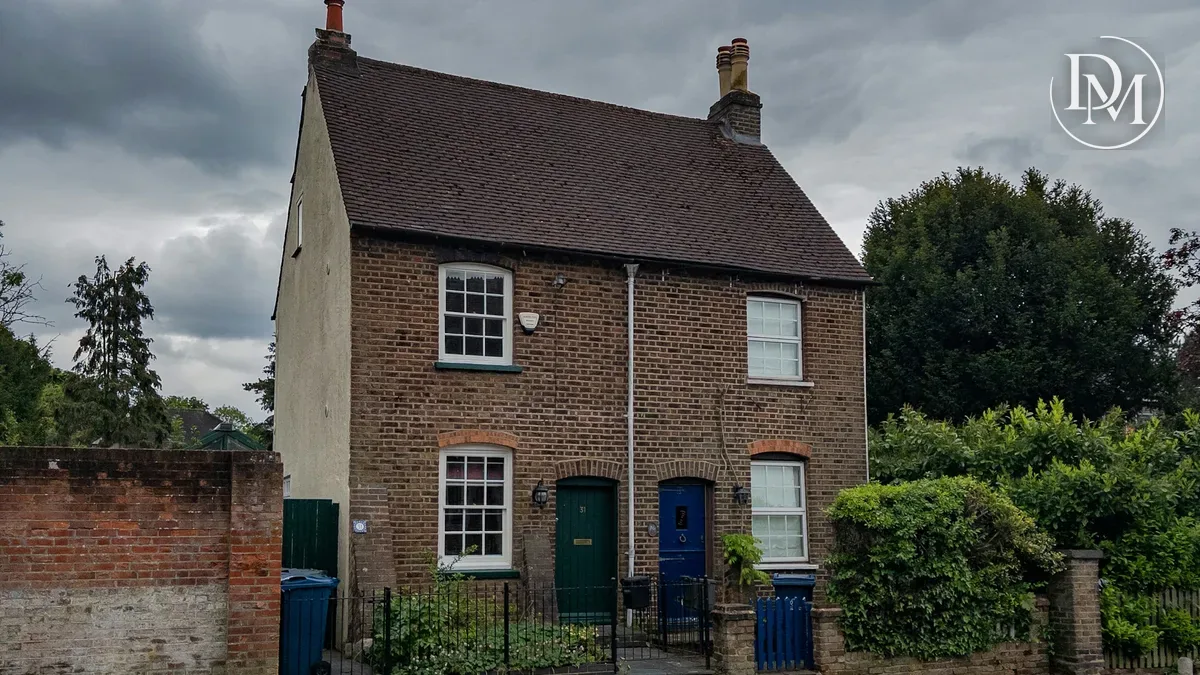
Buying a 2-to-4 Family Home With a VA Loan in Monmouth or Ocean County
Published | Posted by Dennis Mark Interdonato
- Military & VA
- VA Loans
- Multi-Family Homes
- Home Buying
Yes, you can buy a two-, three- or four-family home with a VA loan, as long as the property is going to be your home. VA lists homes of up to 4 units among the things its purchase loan can buy, and its underwriting rules spell out when rent from the other units can help you qualify.
I'm Dennis Mark Interdonato with The Dennis Mark Group at Keller Williams Realty Ocean Living, the Market Center Representative for KW Military, and a former New Jersey home builder and residential remodeler. A multi-family purchase is part home and part rental property, and both halves need a hard look. Here's how VA's rules apply in Monmouth and Ocean County.
Can you use a VA loan on a multi-family property?
VA's purchase loan page (updated January 7, 2026) lists "a single-family home, up to 4 units" among the uses of a VA-backed purchase loan, and VA's Home Loan Guaranty Buyer's Guide says a single-family home, townhouse, or multi-family up to 4 units. Five units and up is outside what the purchase loan describes.
The occupancy rule doesn't change because there are more doors. The same page says you have to live in the home you buy with the loan, and federal law (38 U.S.C. 3704(c)) has you certify at application and closing that you intend to move in personally within a reasonable time. On a two-family, you're one of the households living there. For the details, read VA's occupancy rules.
Does rent from the other units count as income?
It can, with conditions. VA's underwriting rule, 38 CFR 36.4340(f)(12)(i), covers rental income from a multi-unit property you're buying. It says lenders can count prospective rent when:
- You're likely to succeed as a landlord. The lender looks for documentation of prior experience managing rental units or other collection activities.
- You have cash reserves. Verified reserves have to be enough to carry the mortgage payments, without help from the rent, for at least 6 months.
- The rent is discounted. Lenders use 75 percent of the rent shown on the lease or rental agreement, unless a higher percentage can be documented.
That means a buyer with no landlord history, or without six months of payments in the bank, may have to qualify on their own income alone. Ask your lender how it will treat the rent before you start shopping, so we look at the right price range.
How much can you borrow on a 2-to-4 family home?
If you have full entitlement, VA's loan limits page (updated August 12, 2025) says you don't have a loan limit, as long as your lender approves you and the appraisal supports the price. Your income, debts and the lender's standards still set the real number.
If part of your entitlement is tied up in another VA loan, VA tells you to use the county's one-unit limit, even for a multi-unit property. FHFA's 2026 list shows higher limits for two-, three- and four-unit homes in Monmouth and Ocean County, but for VA's remaining-entitlement math the figure is the one-unit limit: $1,209,750 in both counties for 2026. The full calculation is in how remaining entitlement works.
What does a VA appraisal cost on a multi-family home in New Jersey?
VA publishes its appraisal fees and turn times by state. The VA Appraisal Fees and Timeliness table (effective May 1, 2026) lists New Jersey at $800 for a 2-4 unit multi-family home, compared with $650 for a single-family home. The timeliness column is 9 business days for most of the state and 7 for Ocean County, which VA groups with Burlington and Camden.
The appraisal checks value and VA's minimum property requirements. It isn't a home inspection, and VA strongly recommends getting one. Read what a VA appraisal checks.
What should you look at on a two-family house?
This is where my building background earns its keep. With more than one unit, you're inspecting two or more of everything. On a tour, I'm looking at:
- The systems. How many heating systems, water heaters and electric services there are, and how old each one is.
- The structure. The roof, the foundation and the framing carry every unit, so a problem there is everybody's problem.
- The paperwork. The permit history for any conversion work, and the leases, rents and security deposits for any tenant in place.
- The separation. Separate entrances, utilities and meters make the property simpler to run and to rent.
I tell people what they need to hear, not what they want to hear. If a multi-family needs more work than the rent can carry, you'll hear it from me before you write the offer.
How do you buy a multi-family home with a VA loan?
- Get your COE and a pre-approval from a lender who knows VA loans and multi-family underwriting. See how to get your COE.
- Ask how the rent will count, and gather any landlord history and your reserve statements.
- Search with the rent in mind. I'll send multi-family listings as they come up across Monmouth and Ocean County. Browse current listings too.
- Write the offer for a VA loan, with the VA escape clause, an inspection contingency and a request for the leases.
- Inspect every unit, then work through the appraisal, any required repairs and the closing.
Frequently Asked Questions
How many units can you buy with a VA loan?
Up to 4. VA's purchase loan page lists "a single-family home, up to 4 units."
Do I have to live in one of the units?
Yes. VA's occupancy rule still applies, so the property has to be your home.
Can I count the rent from the other units?
Possibly. Under 38 CFR 36.4340, the lender looks at your landlord experience, requires 6 months of reserves, and generally counts 75 percent of the rent.
What does a VA appraisal cost for a 2-4 unit home in NJ?
$800, according to VA's fee table effective May 1, 2026.
This is general information, not legal, tax or lending advice. Your lender decides how rental income counts and what you qualify for. This site isn't affiliated with or endorsed by the Department of Veterans Affairs or the Department of Defense.
About the author
Dennis Mark Interdonato is a REALTOR® and Master CDRE® who leads The Dennis Mark Group at Keller Williams Realty Ocean Living in Point Pleasant, NJ, helping buyers and sellers throughout New Jersey make their next move, with Monmouth and Ocean County as home base. Read more about Dennis Mark, or see how I handle military moves.
Keep reading
- The Military Home Guide
- Townhouse, condo or single-family: what NJ buyers should know
- Selling a home before you buy? Start with what your home is worth.
- Have a question this didn't answer? Send it to Dennis Mark.








